Hi everyone! As we see around this time every year, the IRS has announced higher Health Savings Account (HSA) contribution limits for next year — giving employees (and employers) more room to save tax-free for future medical expenses.
Whether your workforce is already using HSAs or considering enrolling in a high-deductible health plan (HDHP), these updates are an opportunity to reinforce the value of HSAs as part of your benefits strategy.
💡 Why This Matters
HSAs continue to be one of the most powerful tools for managing health-care costs. Contributions are tax-free, growth is tax-free, and withdrawals for qualified medical expenses are tax-free. With rising medical costs, higher contribution limits mean employees can set aside more money to protect themselves and their families.
Let’s talk a wee bit of strategy. Here’s an approach I love, but one we don’t see often enough in my opinion. I call it the expenses now, withdrawals later approach.
Think if you were on an HSA and contributing every year, say 15 years before retirement. During that time, you had medical expenses but NEVER paid them out of your HSA; instead, you saved all of the receipts and paid for everything out of pocket as normal.
Then, when you get to retirement, say you have $20,000 of expenses from the same prior 15 years AND you have receipts for all of those. This is key, SAVE your documentation. At retirement (or anytime you wanted) you could pull that entire $20,000 out of your HSA and it would be non-taxable. Since you already incurred the eligible medical expenses, that money is yours. You are essentially paying yourself back for a “loan” that you gave to your HSA when you initially paid the expenses.
All the while, during the time you left the money in the HSA, your funds were growing and earning interest on a tax-free basis.
Lots of cool strategies are associated with HSAs for those who are planners. This is just one of them. Now to the updates — sorry for the brief diatribe. :)
📈 What’s Changing for 2027?
The IRS released its annual inflation-adjusted limits for HSAs and HDHPs for the 2027 calendar year. Here are the key updates:
HSA Contribution Limits (2027)
-
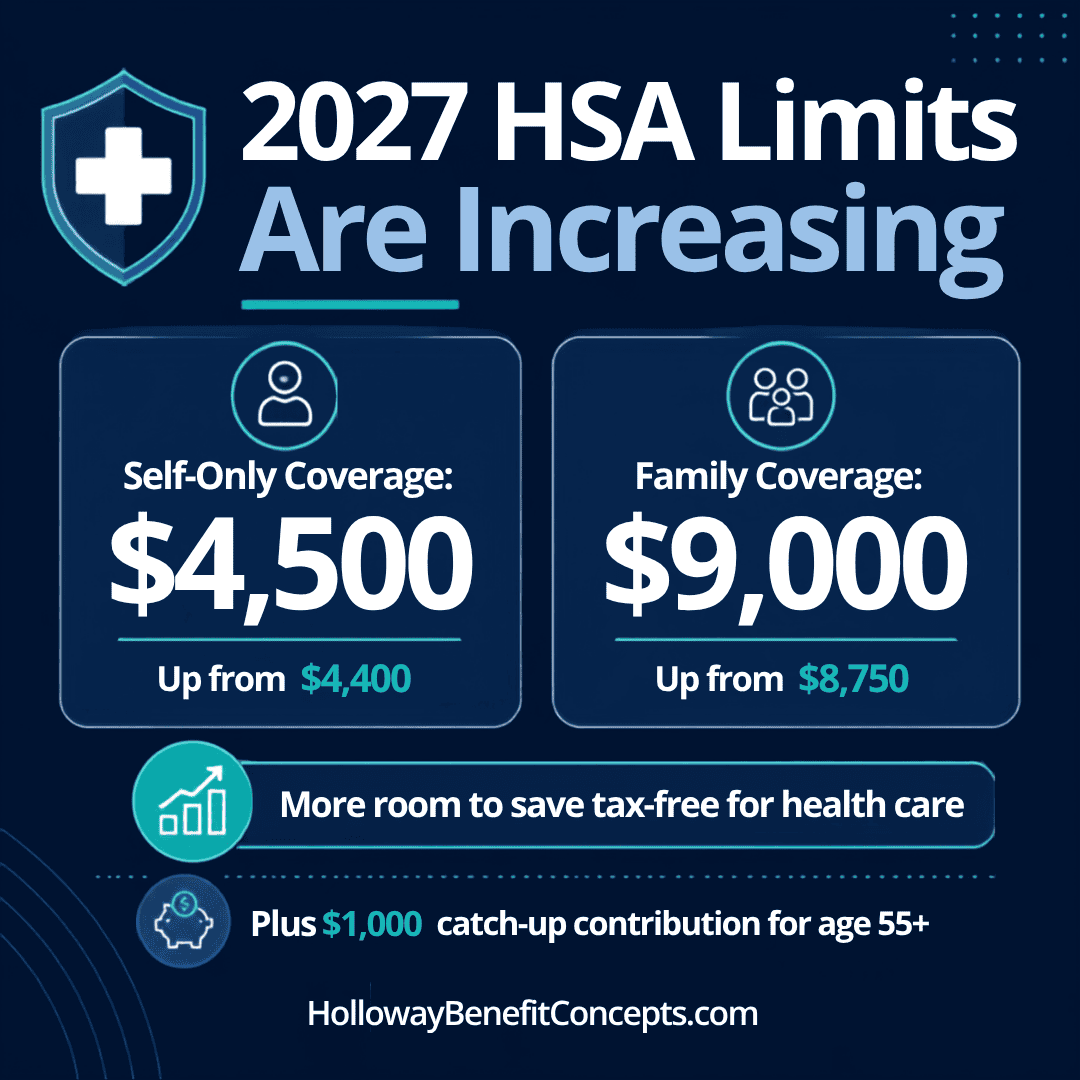
Self-only coverage: $4,500 (up from $4,400 in 2026)
-
Family coverage: $9,000 (up from $8,750 in 2026)
-
Catch-up contribution (age 55+): $1,000 (unchanged — set by statute) – I SOOOOO wish this number would also start seeing regular annual increases!!
HDHP Requirements for 2027 (This is in reference to the medical plan_
To be eligible to contribute to an HSA, employees must be enrolled in an HSA-compatible HDHP. For 2027, those plans must meet these updated thresholds:
-
Minimum deductible:
-
Self-only: $1,750
-
Family: $3,500
-
-
Maximum out-of-pocket expenses:
-
Self-only: $8,700
-
Family: $17,400
-
These adjustments reflect inflation and are designed to keep HSAs aligned with the cost of care which we all know is continuing to skyrocket. I really wish they
🧭 What This Means for Employers
1. Update Your 2027 Benefits Materials
Open enrollment guides, plan summaries, and payroll systems should reflect the new contribution limits and HDHP thresholds.
2. Reinforce HSA Education
Employees often underutilize HSAs simply because they don’t fully understand them. Consider:
-
Hosting short webinars
-
Sharing examples of eligible expenses
-
Highlighting long-term savings benefits (HSAs can function like a retirement account for health care)
3. Review Plan Design
If you offer an HDHP, confirm that deductibles and out-of-pocket maximums align with the 2027 requirements. This ensures continued HSA eligibility and avoids compliance issues.
👥 What This Means for Employees
More Room to Save
The increased limits allow employees to set aside more tax-advantaged dollars — especially valuable for families or those planning for future medical needs.
Better Long-Term Planning
HSAs roll over year to year and can be invested, making them a powerful tool for long-term financial wellness.
Support for Rising Health-Care Costs
As medical expenses continue to rise, HSAs help employees stay prepared and reduce financial stress.
📝 Final H|BC Thoughts
The 2027 HSA updates are a positive change for both employers and employees. Nothing groundbreaking, no major updates or increases, but it’s consistent with what we tend to see year to year from the IRS.
As an employer, by communicating these changes clearly and proactively, you can help your workforce make informed decisions, maximize their benefits, and feel more confident about their health-care planning. HSAs are one of the MOST tax-advantaged tools in anyone’s repertoire. We’d love to see more people using them as long-term savings vehicles.
Any questions or anything we can help with? Please let us know. Thanks for reading!